A returning customer after four years drew a limit-up welcome.
A profitable second quarter still sits beside a loss-making first half.
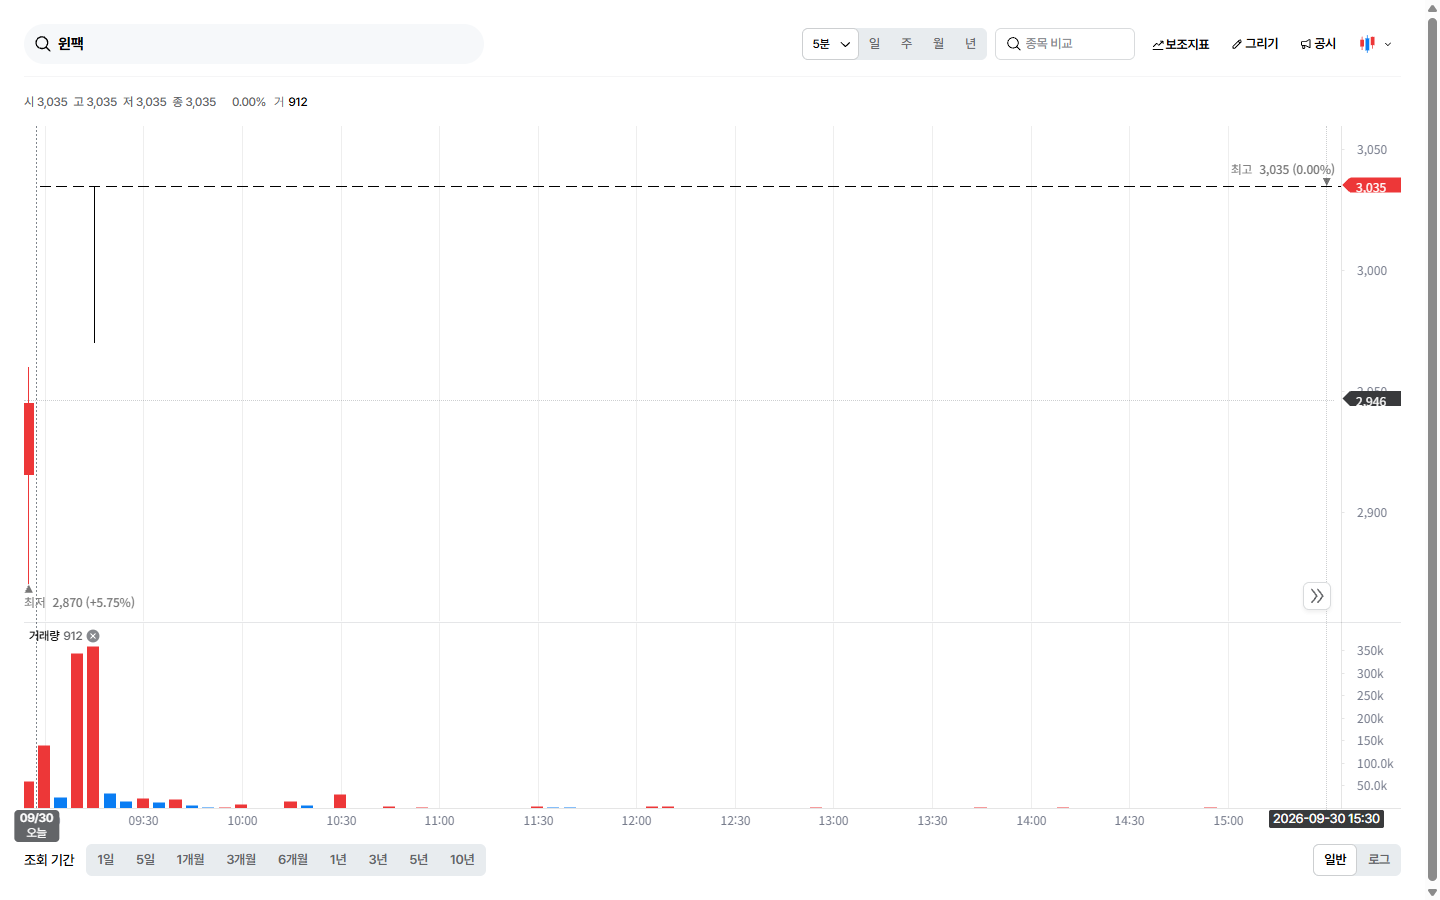
Actual September 30, 2026 five-minute candles covering 09:00–15:30 KST. A few final prior-day candles remain at the left edge.
Company archive photo, not necessarily taken today.
September 30 close: 3,035 KRW (+29.98%) · Volume: 1,094,111 · Turnover: 3,320 million KRW
Why it moved
The Elec reported renewed SK hynix DDR4/DDR5 flip-chip packaging allocation and mass production.
This is industry reporting, not a confirmed direct HBM-order disclosure.
Contract value, duration and minimum volumes were not verified.
Disclosed performance
The August 13 standalone preliminary disclosure reported Q2 revenue of KRW 30.185 billion (+64.5%), operating profit of KRW 795 million and net profit of KRW 127 million.
First-half revenue was KRW 52.370 billion (+59.0%), but operating loss was KRW 1.260 billion and net loss KRW 2.145 billion.
Calculated Q2 operating margin was approximately 2.63%.
Preliminary figures may change upon external review.
Risks to check
Recurring volumes, margins, customer concentration and fixed costs matter.
The Elec’s KRW 110 billion-plus annual revenue is an industry forecast, not a reported result.
A September 21 concentrated-account trading caution was observed, not proof of a current investment-warning designation.
Post-rally volatility remains a risk.
Review-only, not an investment recommendation.
The historical-data discrepancy is unexplained, but today’s close and change were independently matched with Hankyung.